
Editorial note: THAT.MY is responsible for this article. It passed our topic, source, duplication, structure and link checks before publication. Read the editorial policy.
Short answer: Inventory the roof, heating and cooling, plumbing, electrical, exterior and appliances, then map likely timing and cost ranges. Keep routine upkeep separate from major replacements.
A percentage rule can be a starting prompt, but two homes at the same price may have very different near-term needs. Property condition and system age provide better planning signals.
Build the home maintenance reserve estimate
Treat evaluating inspection results and offer price as an evidence check. The estimate needs immediate corrections and routine upkeep for the base case, plus major systems and contingency for the costs that are easiest to omit. The fair comparison is the property-specific work schedule with accessible cash and monthly saving capacity, not whichever option produces the smallest first payment.
| Decision input | What to record |
|---|---|
| Immediate corrections | Use inspection findings that affect safety or damage prevention. |
| Routine upkeep | List recurring service, cleaning and seasonal work. |
| Major systems | Estimate remaining life and replacement ranges. |
| Contingency | Keep margin for hidden damage and timing overlap. |
Do not combine the four inputs into one unexplained total. Keeping immediate corrections separate from contingency makes it possible to change one assumption, identify the break point and ask the provider a precise question before committing.
How the inputs interact: Use inspection findings that affect safety or damage prevention. List recurring service, cleaning and seasonal work. These two entries establish the base case for home maintenance reserve. If they use different dates or time periods, correct that mismatch before adding the remaining costs.
Where uncertainty enters: Estimate remaining life and replacement ranges. Keep margin for hidden damage and timing overlap. Test both statements again after adding two major systems needing work in one year. This shows whether the conclusion depends on a verified term, a household choice or an estimate that still needs evidence.
Questions that expose a weak home maintenance reserve plan
Keep the home maintenance reserve comparison on one timeline
Use this list as a challenge to the base case during evaluating inspection results and offer price. A failed item should change the price, structure, timing or evidence required before proceeding.
- Verify immediate corrections from a written quote or recent record.
- Put routine upkeep on the same timeline as the main payment.
- Test the high end of major systems instead of leaving it blank.
- Write the exit plan for contingency before committing.
Do not treat every inspection item as equally urgent. Separate safety, water intrusion and failure risks from cosmetic preferences.
See home maintenance reserve in a realistic example
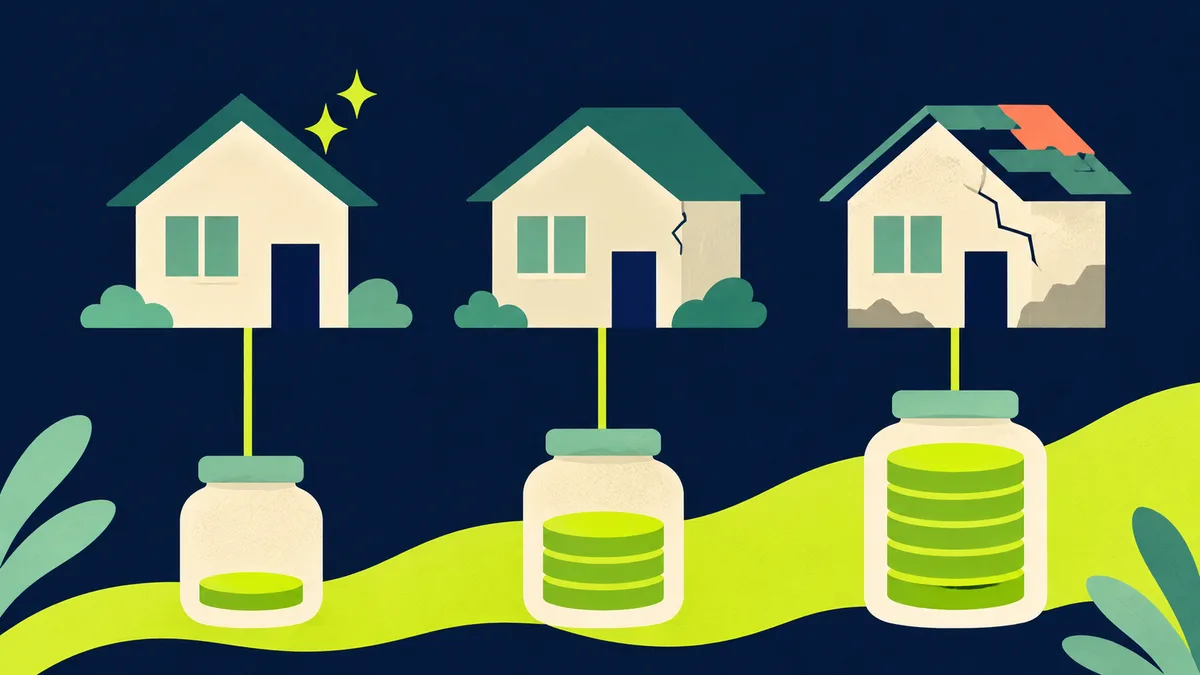
A newer home and an older home share the same price. The older home has a roof and cooling system near expected replacement windows. A lower purchase price may not offset the cash needed during the first three years.
The numbers matter less than the relationship they reveal: condition and timing matter more than applying one percentage to price. Put the actual case through the home ownership cost calculator and keep uncertain costs visible instead of forcing one precise answer.
Stress-test home maintenance reserve before committing
Move next to the total ownership cost guide. Use it to reconcile this decision with saving, existing debt and the cash required after purchase, then keep the final assumptions with the written offer.
Use two major systems needing work in one year as the first practical shock. Then test delayed income and a cost that remains higher every month. One-time and permanent changes should stay separate because a reserve can solve the first but not the second.
Official guidance behind the home maintenance reserve checks
Readers evaluating home maintenance reserve can verify the underlying guidance at the CFPB Closing Disclosure explainer. It separates the estimated monthly payment, closing costs and cash to close, and highlights taxes, insurance and assessments that may sit outside escrow.
The record should make clear that condition and timing matter more than applying one percentage to price. Preserve the assumptions, provider disclosures and downside result. Reopen the decision if the price, timing, income or contract changes materially.